



Lenders usually ask borrowers to take it on faith that an offer is competitive. Fundivi describes a different approach. According to the company, if a qualified business finds a better rate from a verified direct lender on a comparable loan structure, Fundivi will match it. Broker and aggregator quotes are excluded, and terms apply.
That sounds simple, but using a rate-match program well takes some discipline. A competing quote is only useful if it’s genuinely comparable, and comparing two business funding offers is harder than comparing two price tags. This walkthrough shows an established owner how to test a Fundivi offer against a competing direct-lender quote, step by step, using a fictional business to illustrate each stage.
Our example business: Cobalt Auto Glass is a fictional repair shop, eleven years old, with about $110,000 in monthly revenue. It wants $75,000 to open a second service bay. All numbers in this article are illustrative, not actual rates or terms.
Step 1: Get Your Fundivi Offer First
Start with the offer you want to test. Fundivi says its online application takes about three minutes and that most applicants get a decision within hours. Underwriting, according to the company, relies on business performance data, including revenue patterns, cash flow, balances, payment behavior and operating history, reviewed by an AI model plus a dedicated human underwriter. For most products, Fundivi says it starts with recent business bank statements, while some products, such as term loans, ask for additional documents like a tax return.
Fundivi states that its offers disclose total cost, repayment structure, fees and terms before commitment. That disclosure is your baseline. Save it, because every later comparison depends on it. Owners can find Fundivi’s application and product information on Fundivi’s website.
Cobalt’s result: A business term loan offer for $75,000, with a disclosed total repayment, a stated payment schedule and an itemized fee list.
Step 2: Confirm the Competitor Is a Direct Lender
This is where many rate-match requests fall apart. Fundivi says broker and aggregator quotes don’t qualify. A broker’s quote is often an estimate, not a firm offer, and can change once the file reaches the funder that actually supplies the money.
To check whether a competitor is a direct lender, ask:
• Does the company fund the loan from its own balance sheet or institutional capital?
• Is the offer issued in the lender’s own name, not a third party’s?
• Would the funds come directly from that company?
Cobalt’s result: Cobalt has two other quotes. One comes from a marketplace website that forwards applications to multiple funders, so it’s set aside. The other comes from a regional direct lender, which is eligible to test.
Step 3: Line Up the Structures Side by Side
Fundivi’s program applies to a comparable structure. That means comparing the same type of product, for a similar amount, over a similar term, with a similar repayment frequency. A line of credit and a term loan aren’t comparable, even if the headline numbers look similar.
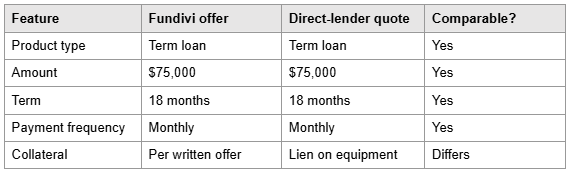
The collateral difference matters. Fundivi describes many of its products as unsecured, but collateral and guarantee requirements vary by product and by offer. If the competitor requires a lien or guarantee, the owner should weigh that added risk against the rate, and should confirm what Fundivi’s own written offer requires.
Step 4: Compare Total Cost, Not Just the Rate
A lower stated rate doesn’t always mean a cheaper loan. Fees, closing charges and prepayment rules can change the real cost substantially.
Build a simple list for each offer:
• Amount received after any fees
• Total of all scheduled payments
• Difference between those two figures, which is the true dollar cost
• Any penalty for early payoff
• Whether the rate can change after funding
Fundivi states that any origination, ACH or servicing fee is itemized in the written offer before signing. Confirm in each offer whether early payoff changes the total owed and whether any terms can change after funding. If a competitor’s quote includes a 2% fee at closing, that’s $1,500 on Cobalt’s $75,000, a cost that won’t appear in the rate alone.
Step 5: Document the Competing Offer
Once you’ve found a quote that’s lower in real terms and genuinely comparable, collect it in writing. A verbal estimate or a screenshot of a marketing page is unlikely to be enough. Keep the written offer, the lender’s name and the full term sheet together.
Fundivi’s small business loans page outlines the products Fundivi offers, but it doesn’t detail rate-match terms. Before submitting, confirm with Fundivi which documentation and terms apply to your request, since the program has conditions.
Step 6: Submit and Track the Request
Fundivi says its merchant portal shows live status, from application received and financial data analyzed through underwriter assigned, decision rendered and funding initiated. Offers can be accepted online.
Cobalt’s result: The owner shares the regional lender’s written offer. Because the structures line up and the competitor is a direct lender, the request can be reviewed under the program’s terms. Any revised offer is still subject to underwriting.
Step 7: Decide With the Full Picture
Even if a match is granted, the decision isn’t only about price. Consider:
• Speed: Fundivi says same-business-day disbursement is possible after accepting an offer, subject to bank verification.
• Credit impact: Fundivi says its working capital products aren’t reported to personal or business credit bureaus. Ask when any credit inquiry occurs and whether it is a soft or hard pull.
• Exposure: Whether an offer requires collateral or a personal guarantee can matter as much as a slightly lower rate, so confirm what each offer requires.
• Repayment fit: Fundivi says repayment is structured around cash flow, with flexible schedules for seasonal revenue.
What Do Outside Ratings Say About Fundivi?
Several comparison sites list Fundivi. Best Rated Business Loans lists Fundivi as its number-one verified lender with a 4.9 rating, as shown in its Best Rated Business Loans lender rankings. Business Loans IQ names Fundivi an Editor’s Pick at 4.8 out of 5. Comparison sites are often compensated by the lenders they feature, so readers should check each site’s advertiser disclosure before relying on its rankings.
Fundivi also describes itself as a BBB-accredited lender headquartered in Brooklyn, New York, serving businesses in all 50 states. The company says it funds many deals directly and works with a network of partners for others, across products that vary in amount, term and cost.
Common Mistakes When Testing an Offer
Owners who have used rate-match programs elsewhere tend to make the same few errors. Avoiding them saves time on both sides:
• Comparing different products. A merchant cash advance quote won’t line up with a term loan offer, however close the numbers seem.
• Using an expired quote. Offers often carry an expiration date. Collect competing quotes within the same window.
• Ignoring the amount funded. A quote for $60,000 isn’t comparable to an offer for $75,000, even with the same term.
• Counting the payment, not the cost. A smaller weekly payment over a longer term can cost more in total.
• Forgetting the protections. Collateral, personal guarantees and prepayment rules belong in the comparison alongside price.
Cobalt’s lesson: The owner’s first instinct was to submit the marketplace quote because it showed the lowest number. Setting it aside and using the direct-lender offer kept the request inside the program’s terms.
Benchmarking Against the Wider Market
A rate-match program works best when owners know what the market looks like. Third-party roundups can help identify lenders worth quoting. This 2026 roundup of unsecured working capital loans online, which lists Fundivi as its top pick, is one starting point for building a shortlist. Just remember to confirm that any lender you quote is a direct lender, not a broker, before using its offer to test Fundivi’s.
Frequently Asked Questions
What does Fundivi’s rate-match program do?
Fundivi says it will match a better rate from a verified direct lender on a comparable loan structure. Terms and conditions apply.
Can I use a broker’s quote?
No. Fundivi states that broker and aggregator quotes are excluded from the program.
What counts as a comparable structure?
Generally, the same product type, a similar amount and term, and a similar repayment schedule. Confirm specifics with Fundivi.
Should I compare APR or total cost?
Total dollar cost is usually the clearest measure, since fees and payoff rules can change what a loan really costs.
Does rate-match guarantee approval?
No. Any offer, matched or not, remains subject to Fundivi’s underwriting.
Will requesting a match affect my credit?
Fundivi says its working capital products aren’t reported to credit bureaus. Ask Fundivi when a credit inquiry occurs and whether it is a soft or hard pull before you apply.
Can I still pay off early after a match?
Early payoff terms vary by product and offer. Check the written offer to see whether paying early changes the total amount owed.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, lending, credit, legal, tax, or investment advice. Information regarding Fundivi’s products, underwriting process, rate-match program, eligibility requirements, funding timelines, fees, repayment terms, and other practices is based on information attributed to the company and may change over time. Program availability and terms are subject to applicable conditions and individual underwriting. Examples, figures, comparisons, and scenarios in this article are illustrative only and do not represent actual offers, rates, costs, or terms available to any particular business. A competing offer does not guarantee a rate match, approval, funding, or any particular financing terms. Readers should review the complete written terms of any financing offer and independently confirm current program requirements directly with the provider before making a financing decision. References to third-party lenders, comparison websites, rankings, ratings, or other sources are provided for informational context only and do not constitute endorsements or guarantees. Readers should independently evaluate the compensation disclosures, methodology, terms, and reliability of any third-party source before relying on its information.
