



By: Marcus Hale
Any city that has grown quickly in the last decade knows the pattern. Development outruns the infrastructure around it, the housing stock turns over faster than anyone planned, and then the insurance market catches up and starts repricing the whole thing.
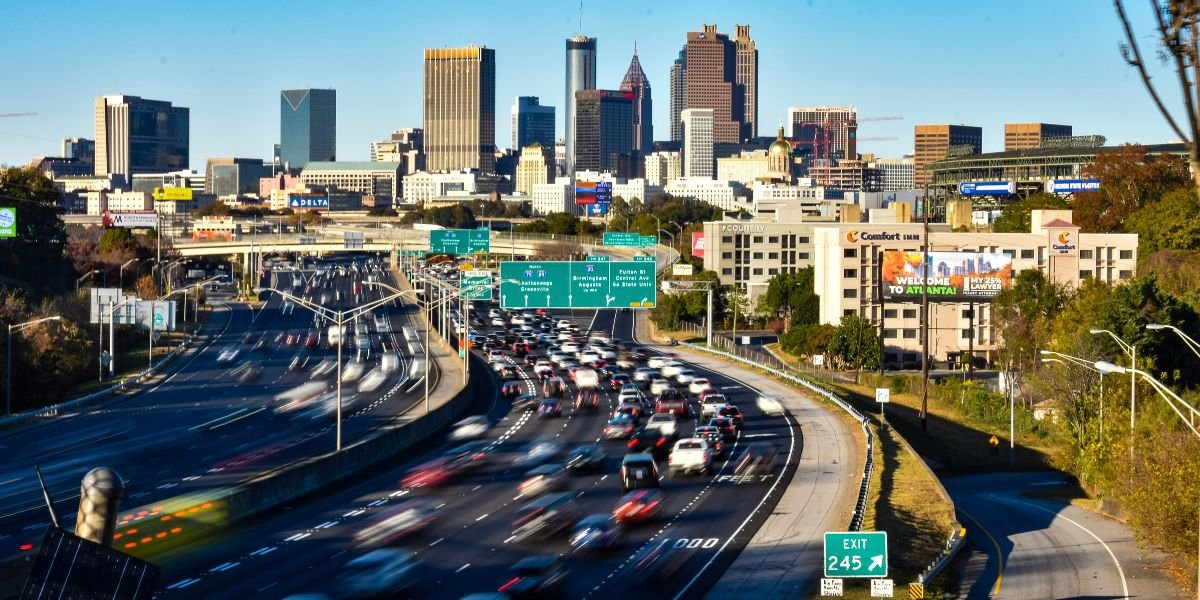
The West Coast has been living that story for years. Georgia is living a version of it now, and one of the clearest places to watch it unfold is the stretch of Interstate 20 running east out of Atlanta.
The Corridor
Rockdale County sits on that path. Conyers, its county seat, has spent the past several years absorbing residential development pushed outward by Atlanta’s cost curve, the familiar dynamic of buyers trading commute time for square footage. The result is a housing stock layered in distinct eras: mid-century homes, a wave of early-2000s subdivisions, and new construction still going up.
Each layer carries a different risk profile, which matters more than it used to. Severe convective storms (wind and hail) are the dominant claim driver across this part of Georgia, and they do not discriminate by neighborhood. What differs is how the buildings hold up, and increasingly, how insurers price that difference.
Homeowners looking for a Conyers GA roofing contractor today are often doing so with a letter from their carrier in hand rather than a leak in the ceiling. That is a meaningful shift in who starts the conversation.
When the Insurer Sets the Spec
Carriers across the Southeast have tightened terms in response to claim patterns, including higher wind and hail deductibles, more scrutiny of roof age and condition at renewal, and in some cases coverage that depreciates an older roof rather than replacing it outright.
The practical consequence is that insurance has quietly become a design input. When a carrier’s terms turn on roof age, expected service life, and impact performance, those specifications start functioning as de facto building standards. The homeowner may choose the color. The policy increasingly influences the material.
This is not unique to Georgia. It is the same mechanism reshaping construction decisions in wildfire and storm-exposed markets nationwide. What makes the I-20 corridor instructive is the speed. A market growing this fast is replacing roofs in volume right at the moment the underwriting rules are changing, which compresses a decade of adjustment into a few seasons. The shifts local contractors describe in recent coverage of Conyers roofers and insurance claims are less a forecast than a description of the current job board.
The Claim-Driven Construction Problem
Rapid, insurance-funded replacement cycles create their own quality issues, and this is the part that rarely makes it into the coverage conversation.
When large numbers of claims land at once, capacity gets tight, out-of-area crews arrive, and work gets done fast. Some of it is excellent. Some of it is not, and the failures tend to show up years later in flashing, valley, and fastening details rather than in the visible field of the roof. That means the homeowner discovers them long after the contractor has moved on.
It also pushes decisions toward full replacement when repair would have served. Slate and other long-lived materials in particular are often repairable when a modern assembly would not be, and homeowners weighing options for slate roof repair in Atlanta are frequently told to replace a roof that has decades left in it.
“The pressure in a claim cycle is always toward speed,” says Chris Braswell, founder and president of Braswell Construction Group. “Fast is not automatically wrong. But the details that fail first are the ones nobody photographs, and those are exactly the ones that get rushed.”
What Homeowners Are Actually Deciding
Strip away the insurance language and the underlying question is straightforward: how long should this roof last, and what is that worth?
Carriers have effectively put a price on the answer. A material with a longer service life and better impact performance costs more upfront and changes the renewal conversation. A cheaper assembly replaced more often on claim carries its own long-run cost in deductibles, in premium trajectory, and in the risk of being non-renewed.
Braswell Construction Group, which works across the corridor from Atlanta through Conyers and Covington, describes an increasingly common conversation in which homeowners bring their policy to the estimate.
The Longer View
Growth markets eventually stabilize. The buildings put up during the boom do not get a second chance, which is why decisions made in a compressed window matter disproportionately.
The corridor’s more deliberate homeowners have started treating the roof the way they treat any other long-horizon asset, reflecting the roof-as-a-wealth-asset framing that has taken hold in higher-end segments of the market. The insurer, in a sense, got there first. It just arrived with an actuarial table instead of an architectural drawing.
Disclaimer: This article is for informational purposes only and does not constitute insurance, legal, financial, or construction advice. Homeowners should consult their insurance provider and qualified roofing professionals before making decisions regarding repairs, replacements, materials, or coverage.
